


Who isn’t? – may be an instinctive reaction – but we do need to take a balanced and objective look at the impact that taxation has on our investments. It is all too easy to fall into an irrational trap of wanting to avoid tax at all costs and in so doing trigger the idiom to “Don’t cut off your nose to spite your face”.
What we want to unpack for you in particular is how Capital Gains Tax [CGT] impacts individual investors. After a period of seven years or more in a growth investment it is likely to reveal a healthy unrealised capital gain [Total value now – less cost of
investment].
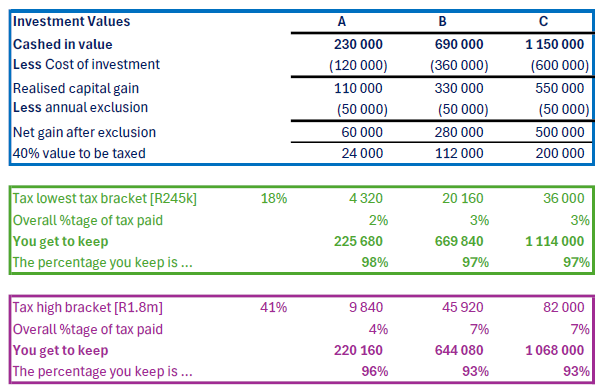
If you cash in that investment the gain becomes realised and will be subjected to tax under the CGT rules. We are granted an annual exclusion of R50,000 … and only gains above that value are taxed. Now for an individual investor it is only 40% of the realised capital gain above the exclusion amount that is included in your tax return and then taxed at your marginal income tax rate. The table below shows three examples – A, B and C – with different values and gains made. It then examines the CGT impact at the lowest tax bracket [Up to R245,000 taxable income] of 18% in green and then for those in the high tax bracket [up to R1.8million income] of 41% in purple. Those green and purple boxes contain the end result with a range of only 2% tax paid on the total cash returned – through to a high of 7% on the cash returned in the case of a very high earner with a large gain of R550,000!
CGT continued … The main triggers for realising capital gains on specific investments within a portfolio are when: – cash from the growth funds is needed to provide monthly cash flows or fund a big expense; it becomes necessary to reduce risk and re-align a portfolio to meet its objectives; a fund, which has performed well in prior years, no longer inspires confidence for the future; it is necessary to restructure the portfolio to fit changed personal circumstances; Then there is one involuntary trigger – when a person dies he/she is deemed to have disposed of all assets at their full market values – and the capital gains made must then be accounted for to SARS. Some extra relief applies on death – we get a R440,000 exclusion instead of just R50,000 and if we leave assets to a surviving spouse, those assets “roll-over” to the spouse at original base cost and will be taxed when the spouse dies. The Primary Residence disposal provides a welcome additional exclusion of R3,000,000 of the capital gain [which applies whenever a Primary Residence is sold].
And the lesson is … Whenever there are good reasons to realise an investment – do NOT be dissuaded from doing so simply because there may well be some additional tax [CGT] to be paid. This is especially so when a fund no longer inspires confidence in its ability to perform well in the future – even if it did well in the past. The World is almost always in a state of flux and that is true not only for the weather but also for the markets. We have wonderful investment diagnostic tools through our Morningstar Direct portal and the algorithms we have built inhouse to sift through their analytical data to rank funds available to our clients for investment. We do not charge any fees for making redemptions from funds or switching between funds already in our care.
Against all odds … We have endured a tumultuous quarter for investors since the end of February 2026 with President Trump and his accomplice, Prime Minister Netanyahu, starting a war with Iran which extends into Lebanon. Destruction on an industrial scale in both of those countries with the death count continuing to rise every day! There seems to be no clear end in sight at time of writing. Despite all that the markets and our client underlying investments are slightly better off than they were at the end of February – which was a particularly high point in both global and local markets. We need an end to this crisis and a complete resumption of energy and goods flows through the Strait of Hormuz and elsewhere within the Middle East to reach destinations throughout the Globe. There will be a negative impact on the Global Economy which will last for many months even if a settlement is reached soon. Fund Managers that we engage with have been proactive in fine tuning their positions to weather the likely consequences but have not made significant changes in view of the fundamentals that remain in place since the beginning of this year. Hopefully we can all look forward to more market “rebounding” in the year ahead – to keep pace with the wave of enthusiasm currently doing the rounds in health “rebounding” … [images created by Copilot, Microsoft’s AI offering embedded within their Edge Browser]
Do get in touch with us – we are here to assist you and are just a phone call away.
